Account age is how long your credit accounts have been open. Each account on your credit report shows the date it was opened, and credit scores use those dates to measure how long you've been managing credit. Older accounts give a lender a longer record to look at, which tends to help your score. To see your own account ages, look at the date opened on each account in your credit reports.
- Account age is how long your credit accounts have been open. Each account on your credit report lists the date it was opened.
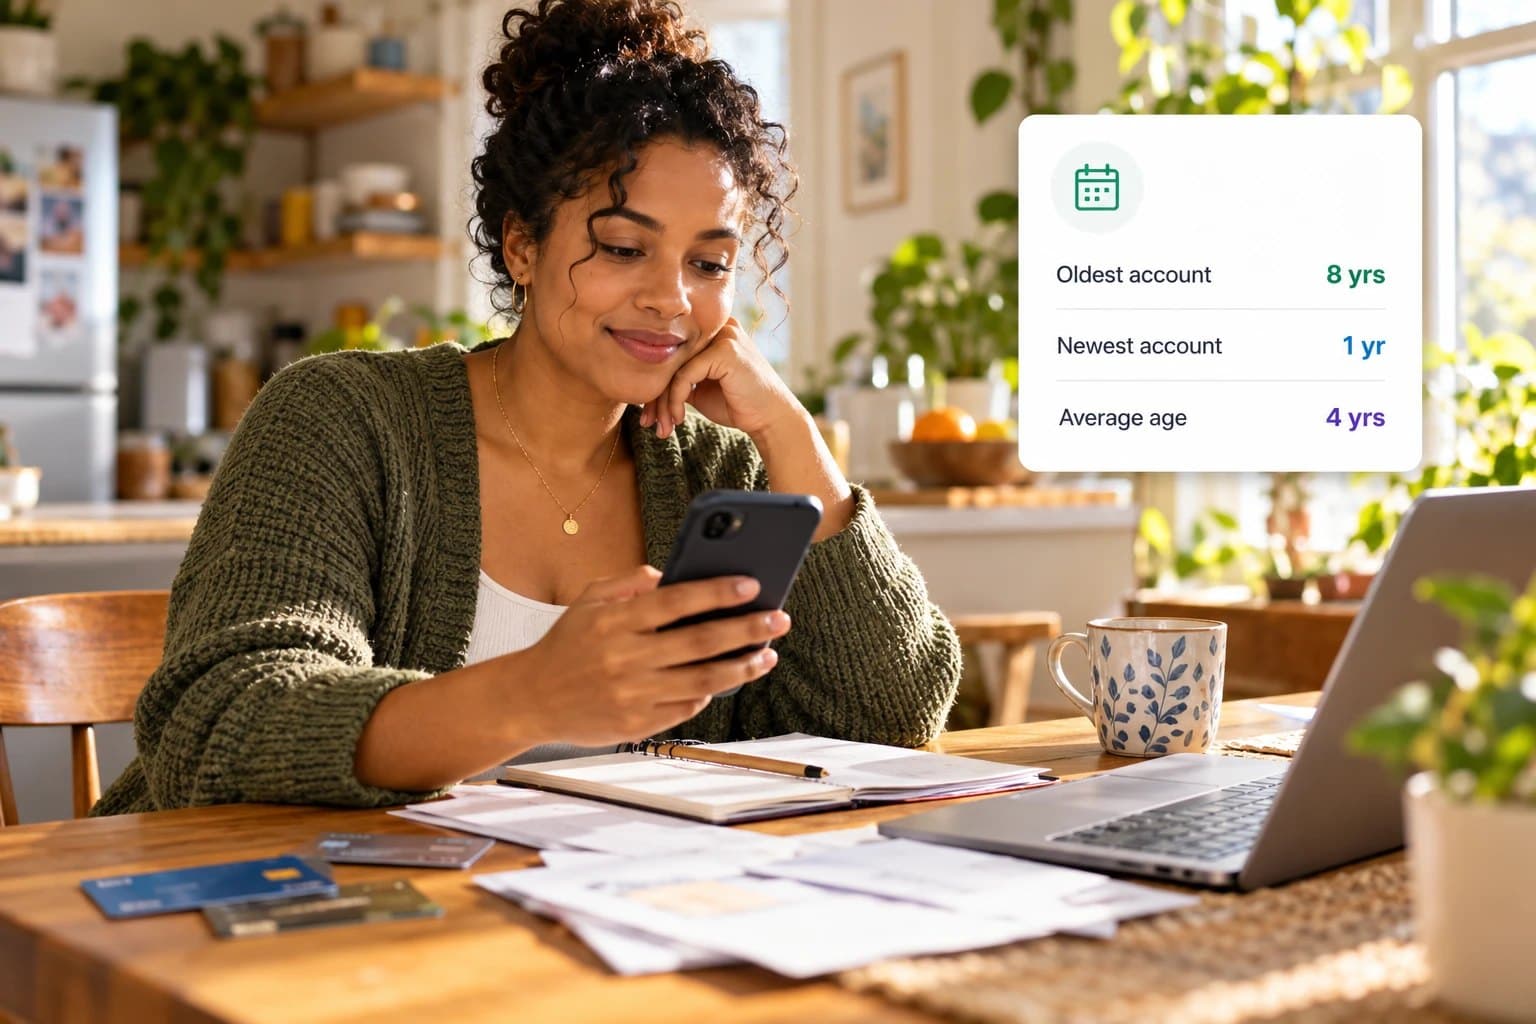
- Credit scores look at more than one age: your oldest account, your newest account, and the average age of all of them.
- Opening a new account lowers your average age. Closing an account in good standing does not erase its age right away, because closed accounts can stay on your report for up to 10 years. Closing a card can still hurt in another way, by raising the share of your credit limits you're using.
- Age builds only with time. You can't rush it, but you can avoid shrinking it by accident.
Why do credit scores care how old your accounts are?
A credit score is a lender's shortcut for one question: how likely is this person to pay what they borrow? Account age adds time to the answer. Ten years of on-time payments says more than ten months of on-time payments, because a longer record has been through more of real life. Some lenders also look straight at the age of the oldest account on your credit reports when you apply.
Account age is not your own age. Credit scores don't use how old you are, and a 22-year-old and a 52-year-old who each opened their first card last year have the same account age on that card.
Which ages actually count?
"Account age" sounds like one number, but scores look at several. The two major scoring models, the formulas that turn a credit report into a score, are FICO and VantageScore. Both consider:
- The age of your oldest account.
- The age of your newest account.
- The average age of all your accounts.
FICO also looks at how long specific accounts have been open and whether certain accounts have been used recently. When people say "the length of your credit history," this group of measurements is what they mean.
How much it weighs depends on the model. FICO says length of credit history makes up about 15% of its score. VantageScore 4.0 puts account age inside a factor it calls depth of credit, which also covers your mix of card and loan accounts, and weights that factor at about 20%. The two numbers don't line up exactly, because VantageScore's figure includes more than age. In both models, payment history carries the most weight, so paying on time matters more than how long you've had the account.
How the average works, with an example
Hypothetical example: say you have a credit card you opened 8 years ago, a car loan from 3 years ago, and a second card from 1 year ago. Add the ages and divide by the number of accounts: 8 + 3 + 1 = 12 years, divided by 3 accounts, is an average of 4 years.
| Before | After opening a new card | |
|---|---|---|
| Oldest account | 8 | 8 |
| Newest account | 1 | 0 |
| Number of accounts | 3 | 4 |
| Average age | 4 (12 ÷ 3) | 3 (12 ÷ 4) |
Now you open a new card today. Its age is zero, so the total stays at 12 years but is spread across 4 accounts. Your average drops from 4 years to 3, and your newest account is now brand new. Your oldest account didn't change at all. This is why a new account can dent the age part of a score even when nothing went wrong.
What happens to account age when you close an account?
At first, not much. FICO and VantageScore both count closed accounts when they measure age, for as long as those accounts stay on your credit report. An account you closed in good standing, meaning it wasn't past due, generally stays on your report for up to 10 years. An account that was past due when it closed comes off seven years after the first missed payment in the run that led to the closure, not seven years from the day it closed. That shorter clock isn't a perk: the late payments on that account count against you the whole time it's there.
The age effect shows up later, when a closed account finally drops off your report. After that, it can't count toward your account age anymore. If it was your oldest account, your oldest age resets to whatever account is next in line.
Can you make your accounts older?
Not directly. Time is the only thing that ages an account. What you can control is not shrinking your average by accident:
- Open new accounts when you need them, not for a quick reward. Each one lowers your average age and adds a new "newest account."
- Think twice before closing your oldest card, mostly because of the utilization effect above and because its age stops counting once it leaves your report.
- Keep paying on time. An old account with a clean payment record is the combination scores are built to reward.
Being added as an authorized user, when a cardholder such as a parent or partner adds you to their card, is one more way an older account can appear on your report. It works both ways, though: that account's late payments or high balances can show up on your report too, and newer FICO versions give authorized-user accounts less weight than accounts in your own name.
If your credit is new
A short history isn't a black mark the way a late payment is. It just means your credit report has less to show so far. To generate a FICO Score, your credit report generally needs at least one account that has been open for six months or more and at least one account that has been reported to the bureau within the past six months. A newer credit report can still score well if the rest of it looks good. Pay on time, keep card balances low, and let the months add up.
Where to find your account ages
Every account in the accounts section of your credit report lists a date opened, as reported by the lender, along with whether the account is open or closed. Closed accounts are part of the list, so check those dates too. Equifax, Experian, and TransUnion each keep a separate report, so check all three.
Common questions
Does paying off a loan lower my account age?
Not right away. A paid-off loan, like a car loan or student loan, shows as closed, and closed accounts still count toward age for as long as they stay on your report. A loan paid as agreed can remain there for up to 10 years after it closes.
Is a longer credit history always better?
Longer tends to help, but only alongside the other factors. An old account with late payments won't help the way an old account paid on time does, and a newer credit report with a clean record can still score well.
Sources
Checked September 30, 2026
- myFICO, How Length of Credit History Affects Your FICO ScoreLength of credit history is about 15% of a FICO Score; it considers the oldest, newest, and average account age, how long specific accounts have been open, and how long since some were used; newer files can still score well.
- myFICO, How to Decide Whether It's Time to Close a Credit CardFICO Scores consider the age of open and closed accounts; a closed card stops helping length of credit history once it leaves the report.
- myFICO, What are the minimum requirements for a FICO Score?At least one account opened for six months or more, and at least one account reported to the bureau within the past six months, are needed for a FICO Score.
- myFICO, How do authorized user accounts impact the FICO Score?Authorized user accounts can appear on the user's report, positive and negative information both count, and recent FICO versions give them less weight than primary accounts.
- VantageScore, Is Age a Factor in Your Credit Score?Personal age is not a scoring factor; VantageScore considers the oldest, youngest, and average account age.
- VantageScore, The Complete Guide to Your VantageScoreVantageScore 4.0 weights: payment history 41%, depth of credit 20%; depth of credit covers average, oldest, and youngest account age plus the mix of revolving and installment accounts.
- Experian, How Long Do Closed Accounts Stay on Your Credit Report?Closed accounts not past due generally stay up to 10 years; past-due closed accounts come off seven years after the original delinquency date (the first missed payment in the series); FICO and VantageScore consider closed accounts in age factors.
- Experian, Does Closing a Credit Card Hurt Your Credit?Closing a card removes its limit and can raise utilization; some issuers close inactive accounts.
- Experian, Understanding Your Experian Credit ReportEach account lists a date opened as reported by the creditor, and an account status such as open or closed.
- myFICO, How Payment History Impacts Your Credit ScorePayment history is the largest FICO Score factor.
- Experian, How Does Length of Credit History Affect Credit Score?Opening new accounts lowers average account age; being added as an authorized user can help build length of credit history.
- Equifax, Credit Report TerminologyAccount age is the length of time a credit account has been open; some lenders look at the age of the oldest account.
This page is general information, not financial or legal advice.